
More news on this day
Saudi Arabia’s effort to reinvent itself as a global tourism powerhouse is entering a more sober phase, as cost pressures, project cuts and shifting priorities reshape the kingdom’s headline-grabbing Vision 2030 plans.
Get the latest news straight to your inbox!
From megaproject hype to measured retrenchment
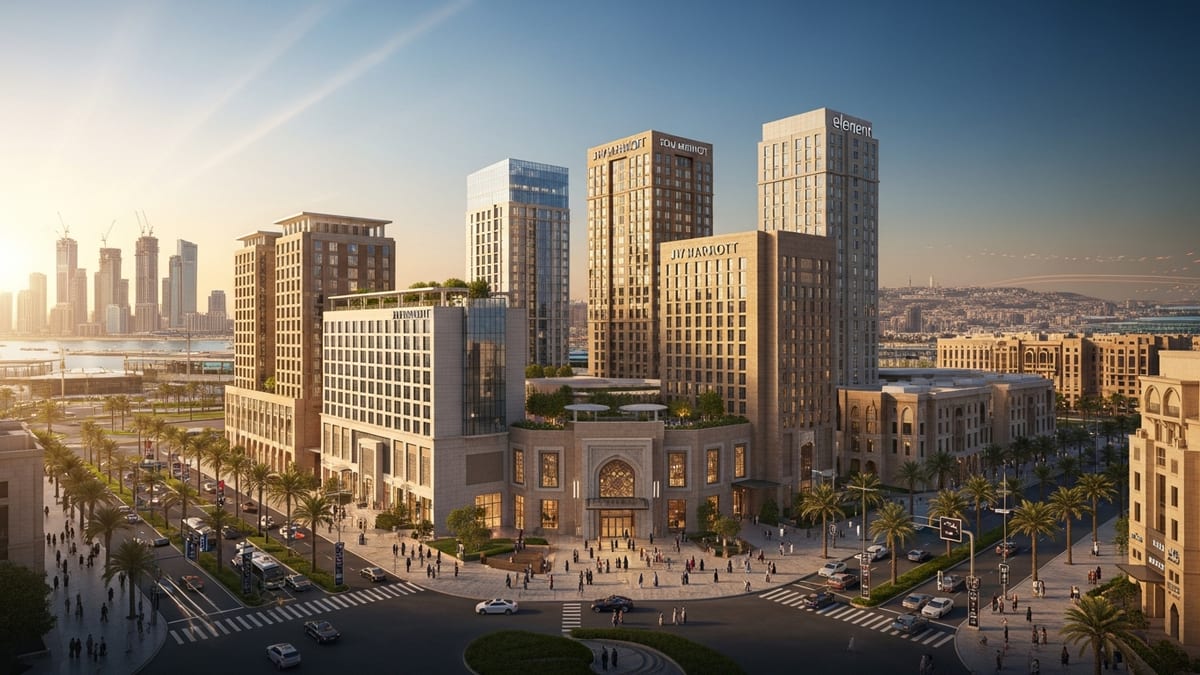
For much of the past decade, Saudi Arabia’s tourism narrative was defined by spectacle. Futuristic cities in the desert, ski resorts in mountain ranges and cube-shaped downtown districts were presented as proof that the kingdom could leapfrog into the tourism big league almost overnight. These projects were bundled into Vision 2030, the sweeping economic transformation agenda championed by Crown Prince Mohammed bin Salman.
By 2024 and 2025, however, publicly available information showed that reality was catching up with the most ambitious elements of the programme. Reporting on Neom’s flagship city, The Line, indicated that internal targets for 2030 were quietly scaled back, with shorter initial sections and far fewer residents than originally promoted. Industry publications tracking contracts in the kingdom also described a slowdown in new awards linked to several giga-projects, suggesting that financing capacity and delivery timelines were being reassessed.
Specialist analysis of the Vision 2030 pipeline in 2025 and 2026 pointed to a pattern rather than isolated cases. High-cost, long-horizon concepts such as The Line, Trojena and New Murabba’s Mukaab were repeatedly cited as being under review, while contracts for tunnel sections and other technically complex components were cancelled or renegotiated. Commentators framed this as a “reality check” on the era of megaproject euphoria, with planners under pressure to concentrate on projects that can start generating tourism revenue within the current decade.
At the same time, the government’s own Vision 2030 reporting has emphasised aggregate progress, noting that the majority of tracked initiatives across the programme are on or near target. That contrast between system-wide indicators and highly visible project resets has fuelled debate over whether Saudi Arabia’s tourism dream is faltering or simply entering a more pragmatic second chapter.
Neom, The Line and the symbolism of scaling back
Nowhere has that debate been more intense than around Neom, the vast development zone on the Red Sea coast near the Jordanian and Egyptian borders. The Line, marketed as a 170 kilometre-long zero-car linear city, became a global symbol of Saudi Arabia’s transformation and a centrepiece of its tourism ambitions.
In practice, the construction story looks more incremental. Analyses drawing on contractor announcements and satellite imagery describe work concentrating on a short pilot stretch of The Line, with excavation and foundation works focused on a segment of a few kilometres rather than the full length. Trade media in 2024 and 2025 reported that contracts for some tunnel sections were cancelled and that internal cost estimates had risen sharply, reaching levels that would vastly exceed earlier budget signals.
Additional coverage in 2025 suggested that an internal audit presented to Neom’s board concluded the original full build-out would require several trillion dollars in spending and would not be fully delivered until well beyond mid-century. While those figures have not been detailed in official Saudi documents, subsequent public messaging around Neom has shifted toward more near-term components such as the Sindalah island resort and specific tourism zones, rather than the entire 170 kilometre city concept.
These changes have been interpreted internationally as evidence of retreat. Within the broader Vision 2030 framework, however, Neom’s partial recalibration is often characterised as a sequencing decision, designed to prioritise projects with clearer revenue potential before committing to the most capital-intensive urban experiments. For travellers, the practical implication is that Neom is likely to emerge first as a cluster of luxury coastal and mountain destinations, with the more radical cityscape remaining a longer-term possibility.
Tourism growth continues, but the mix is shifting
Despite the turbulence around megaprojects, Saudi Arabia has continued to post strong headline tourism numbers. Official Vision 2030 updates have highlighted a revised target of 150 million visitors a year by 2030, raised from an earlier goal of 100 million. International organisations tracking travel flows have also recorded a sharp rise in arrivals in the years following the launch of the tourist e-visa in 2019.
The government’s National Tourism Strategy places tourism at the centre of diversification, and reforms have followed. According to information published by Saudi authorities, citizens from more than 60 countries are now eligible for an e-visa or visa-on-arrival for leisure, business and Umrah travel. A tourist visa handbook issued through diplomatic channels lists the standard fee at 440 Saudi riyals plus value added tax and payment charges, providing travellers with transparent baseline costs.
At the product level, the story has moved beyond blueprints. Heritage-led developments such as Diriyah, near Riyadh, and the restoration of historic AlUla in the northwest have opened hotels, museums and event venues that attract both regional and long-haul visitors. On the Red Sea, new luxury resorts under the Red Sea Global umbrella, including properties managed by international brands, have begun receiving guests, with additional phases under construction on nearby islands.
Analysts note that these operational destinations, along with religious tourism in Mecca and Medina and an expanding calendar of concerts and sporting events, are responsible for most of the near-term growth in visitor spending. In this reading, Saudi tourism is gradually diversifying through a mix of heritage, nature and events, even as some of the most futuristic city concepts are pushed further into the future.
Global events and competitive pressure
Part of the kingdom’s tourism calculus now hinges on two fixed dates: Expo 2030 in Riyadh and the 2034 FIFA World Cup, which Saudi Arabia is set to host. Construction and investment priorities across the country are increasingly being aligned with these milestones, with planners favouring projects that can realistically be delivered and activated within that window.
Industry forecasts suggest that Expo 2030 could generate a wave of demand for accommodation, transport and entertainment in Riyadh, while the World Cup is expected to spread benefits across multiple host cities. This hard deadline dynamic helps explain why certain giga-projects have been scaled back or paused, while others tied to event readiness, such as airport expansions and urban infrastructure upgrades, are moving ahead more decisively.
At the same time, Saudi Arabia is entering a crowded field. Destinations such as Dubai, Abu Dhabi, Doha and established leisure markets in the Mediterranean and Indian Ocean already compete aggressively for high-spending travellers. Analysts writing on the Gulf’s tourism economy emphasize that Saudi resorts on the Red Sea and new urban entertainment districts must match or surpass existing benchmarks on service, pricing and accessibility if they are to draw repeat international visitors rather than one-off curiosity trips.
This competitive landscape leaves little room for missteps. While bold architecture has helped keep Saudi Arabia in the global headlines, success over the next decade is likely to be judged on more prosaic metrics: flight connectivity, hotel performance, perception of social openness and the ease with which visitors can move around the country.
A reset rather than an end to the tourism dream
The question facing policymakers and investors in late 2026 is not whether Saudi Arabia is still betting on tourism, but what kind of tourism model ultimately emerges. Reports from construction and finance sectors point to a more selective approach, in which capital is increasingly channelled to projects with clearer demand and shorter payback periods, while experimental megastructures are slowed, resized or repackaged.
Critics argue that the scale-backs at Neom and other giga-projects expose structural risks in attempting to build entirely new destinations in a compressed timeframe, particularly in a country still undergoing rapid social and regulatory change. Supporters counter that even a partial delivery of the original Vision 2030 tourism map would represent a dramatic expansion compared with Saudi Arabia’s position a decade ago, when it was largely closed to non-religious visitors.
For travellers watching from abroad, the picture is nuanced. On one hand, the most eye-catching renderings of mirrored skyscraper cities and gravity-defying stadiums are unlikely to be fully realised by 2030. On the other, new heritage quarters, desert retreats and Red Sea resorts are already on booking platforms, and marquee events are locked into the global calendar.
Rather than the end of Saudi Arabia’s tourism dream, the emerging pattern suggests a transition from utopian masterplans to incremental, revenue-focused delivery. The coming years will show whether that recalibrated strategy can convert sustained infrastructure spending and regulatory reform into a durable place for Saudi Arabia on the world tourism map.